

Let’s review why we are down in Las Vegas Sands.
I invested at $46/share in May 2024.
Including dividends I’m down 14% through October 2026.
Let’s review what we expected when we invested and how that played out. I think you’ll find the trends in quarterly gaming data for Singapore and Macau are useful to see.
The LVS investment in 2024 was part of a broader investment into China at the bottom of the property crisis in 2024; when China was uninvestable. In 2024 the Chinese government was finally panicking and starting to stimulate the economy. We bought into LVS, Ping An, Tencent, Baidu, Alibaba and Hong Kong Exchange. Earlier this year we sold Alibaba and Baidu, but still own Tencent, Ping An, LVS and Hong Kong Exchange.
My expectation at the time was China would stimulate its economy similar to the US post GFC and we would get a recovery in the stock market, consumer confidence and Macau Gaming volumes.
Longer term the attraction was to be exposed to growing wealth across Asia. LVS has the 5 casinos in Macau, but also the crown jewel, Marina Bay Sands (MBS) in Singapore. That one casino makes more than the other 5 in Macau combined. In 2025 Marina Bay Sands earned an EBITDA of $2.9 billion, which is kind of shocking for one building.
Below are the revenue expectations from when we first built our model in August 2024.

So why are we -14% on our investment 2 years later?
What happened? What went wrong?
Below are the actual revenues along with our current forecasts.

You can see 2024 and 2025 revenues came in as expected, but 2026 is offtrack and has dragged down the 2027 and 2028 estimates.
Instead of $14,459 million in revenues for 2026 it’s likely to be $13,321 million. That prior $14.5bn revenue forecast for 2026 isn’t even on the map any more.
Look how the mix played out.
Macau has been dead as dirt while Singapore shot the lights out.
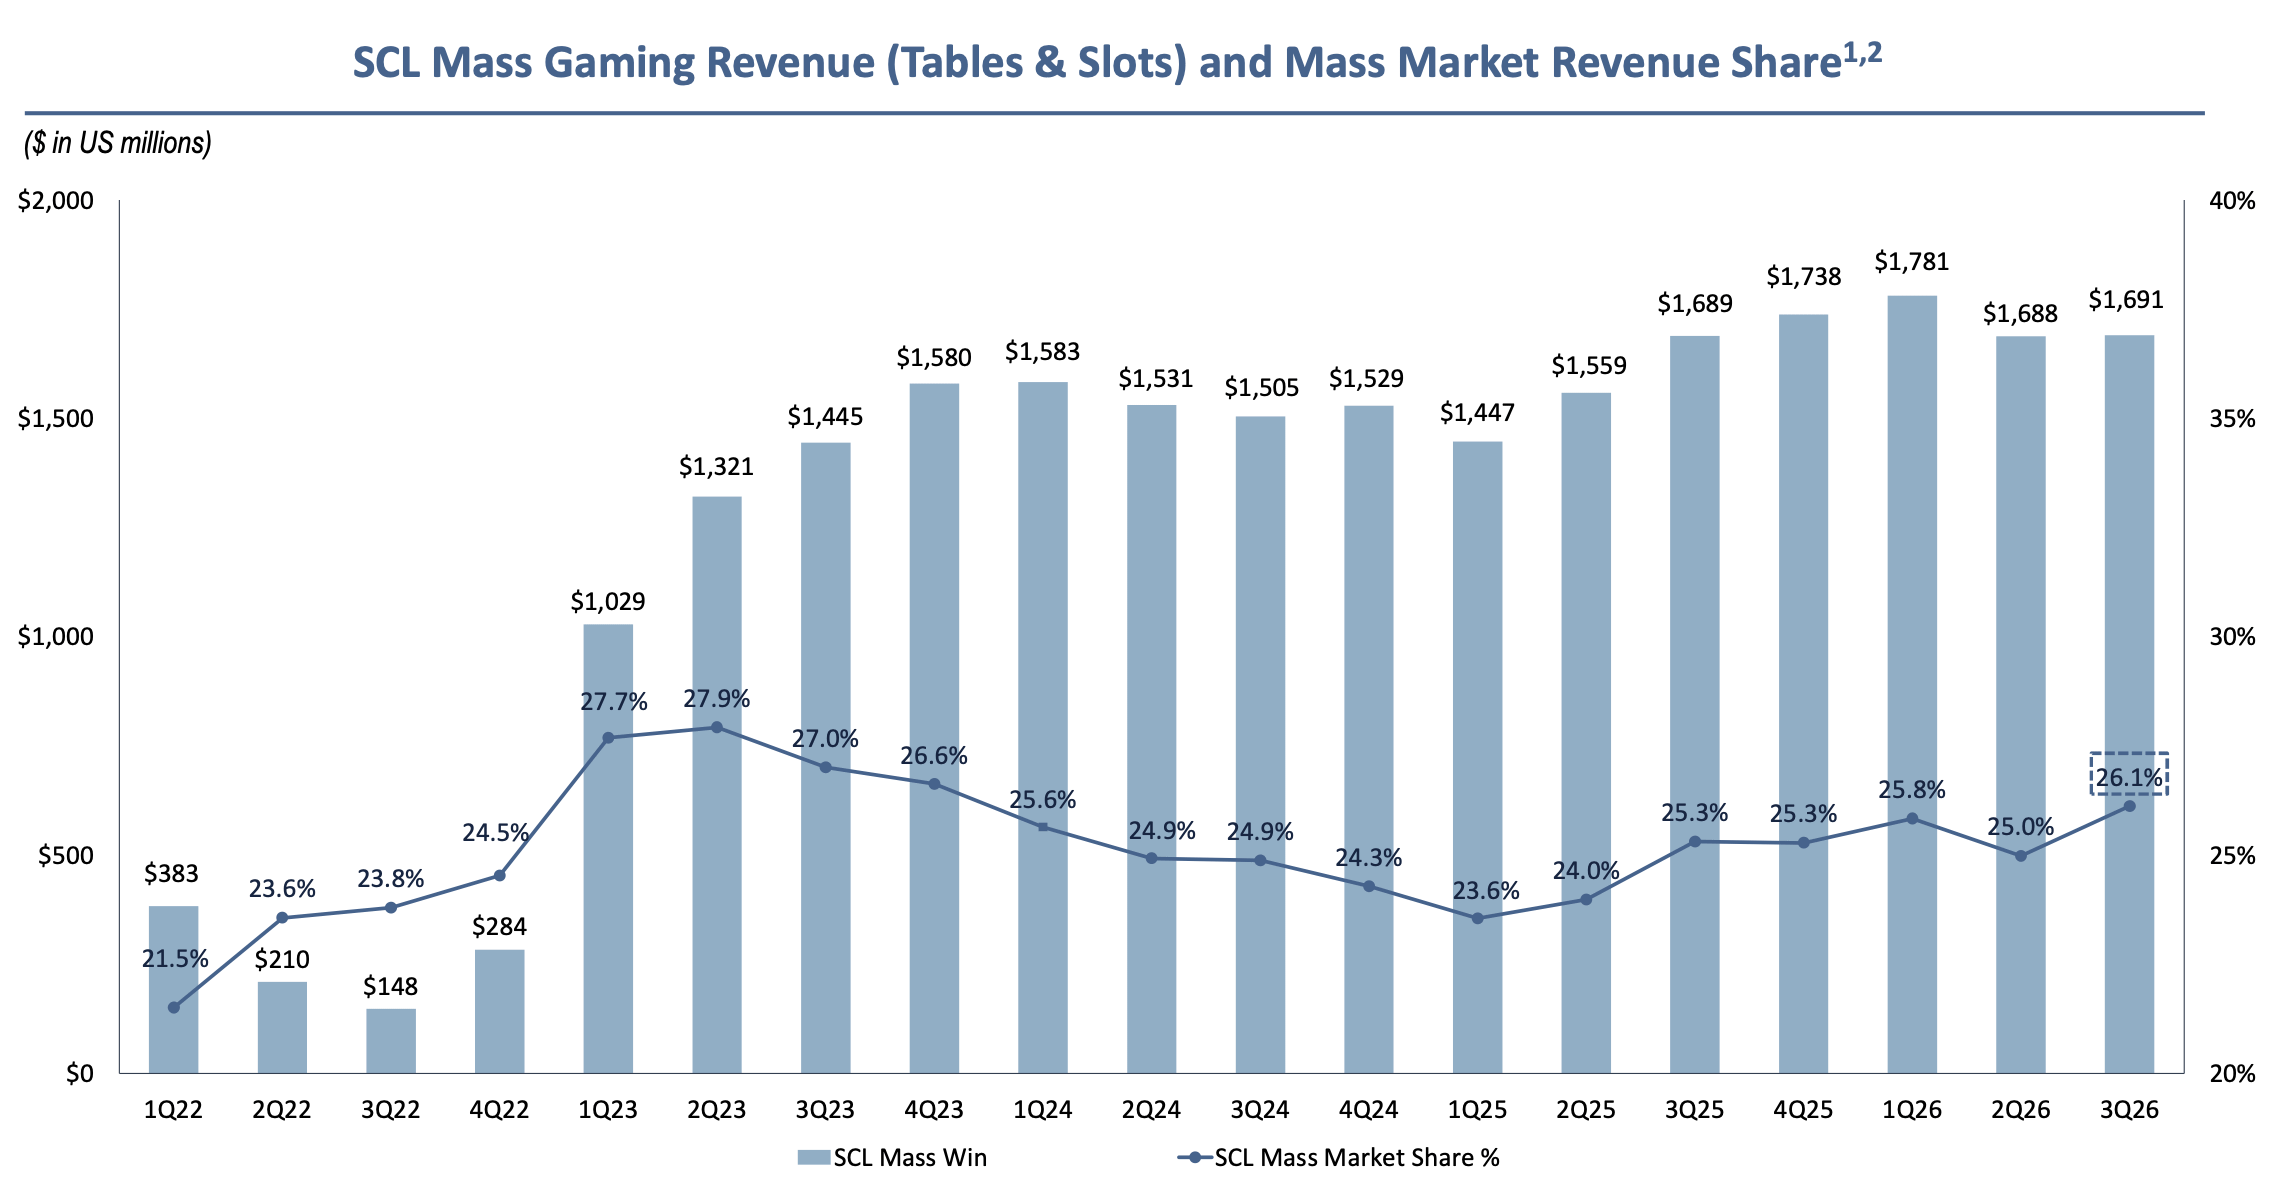
We were expecting Macau could rebound from $6.5bn to potentially $9.2 billion by 2026. Instead Macau has been sluggish at $7.6bn.
Below is the LVS earnings slide for Sands China quarterly gaming revenues. You see Macau has been a real grind. And this is with major renovations to the Londoner Casino.
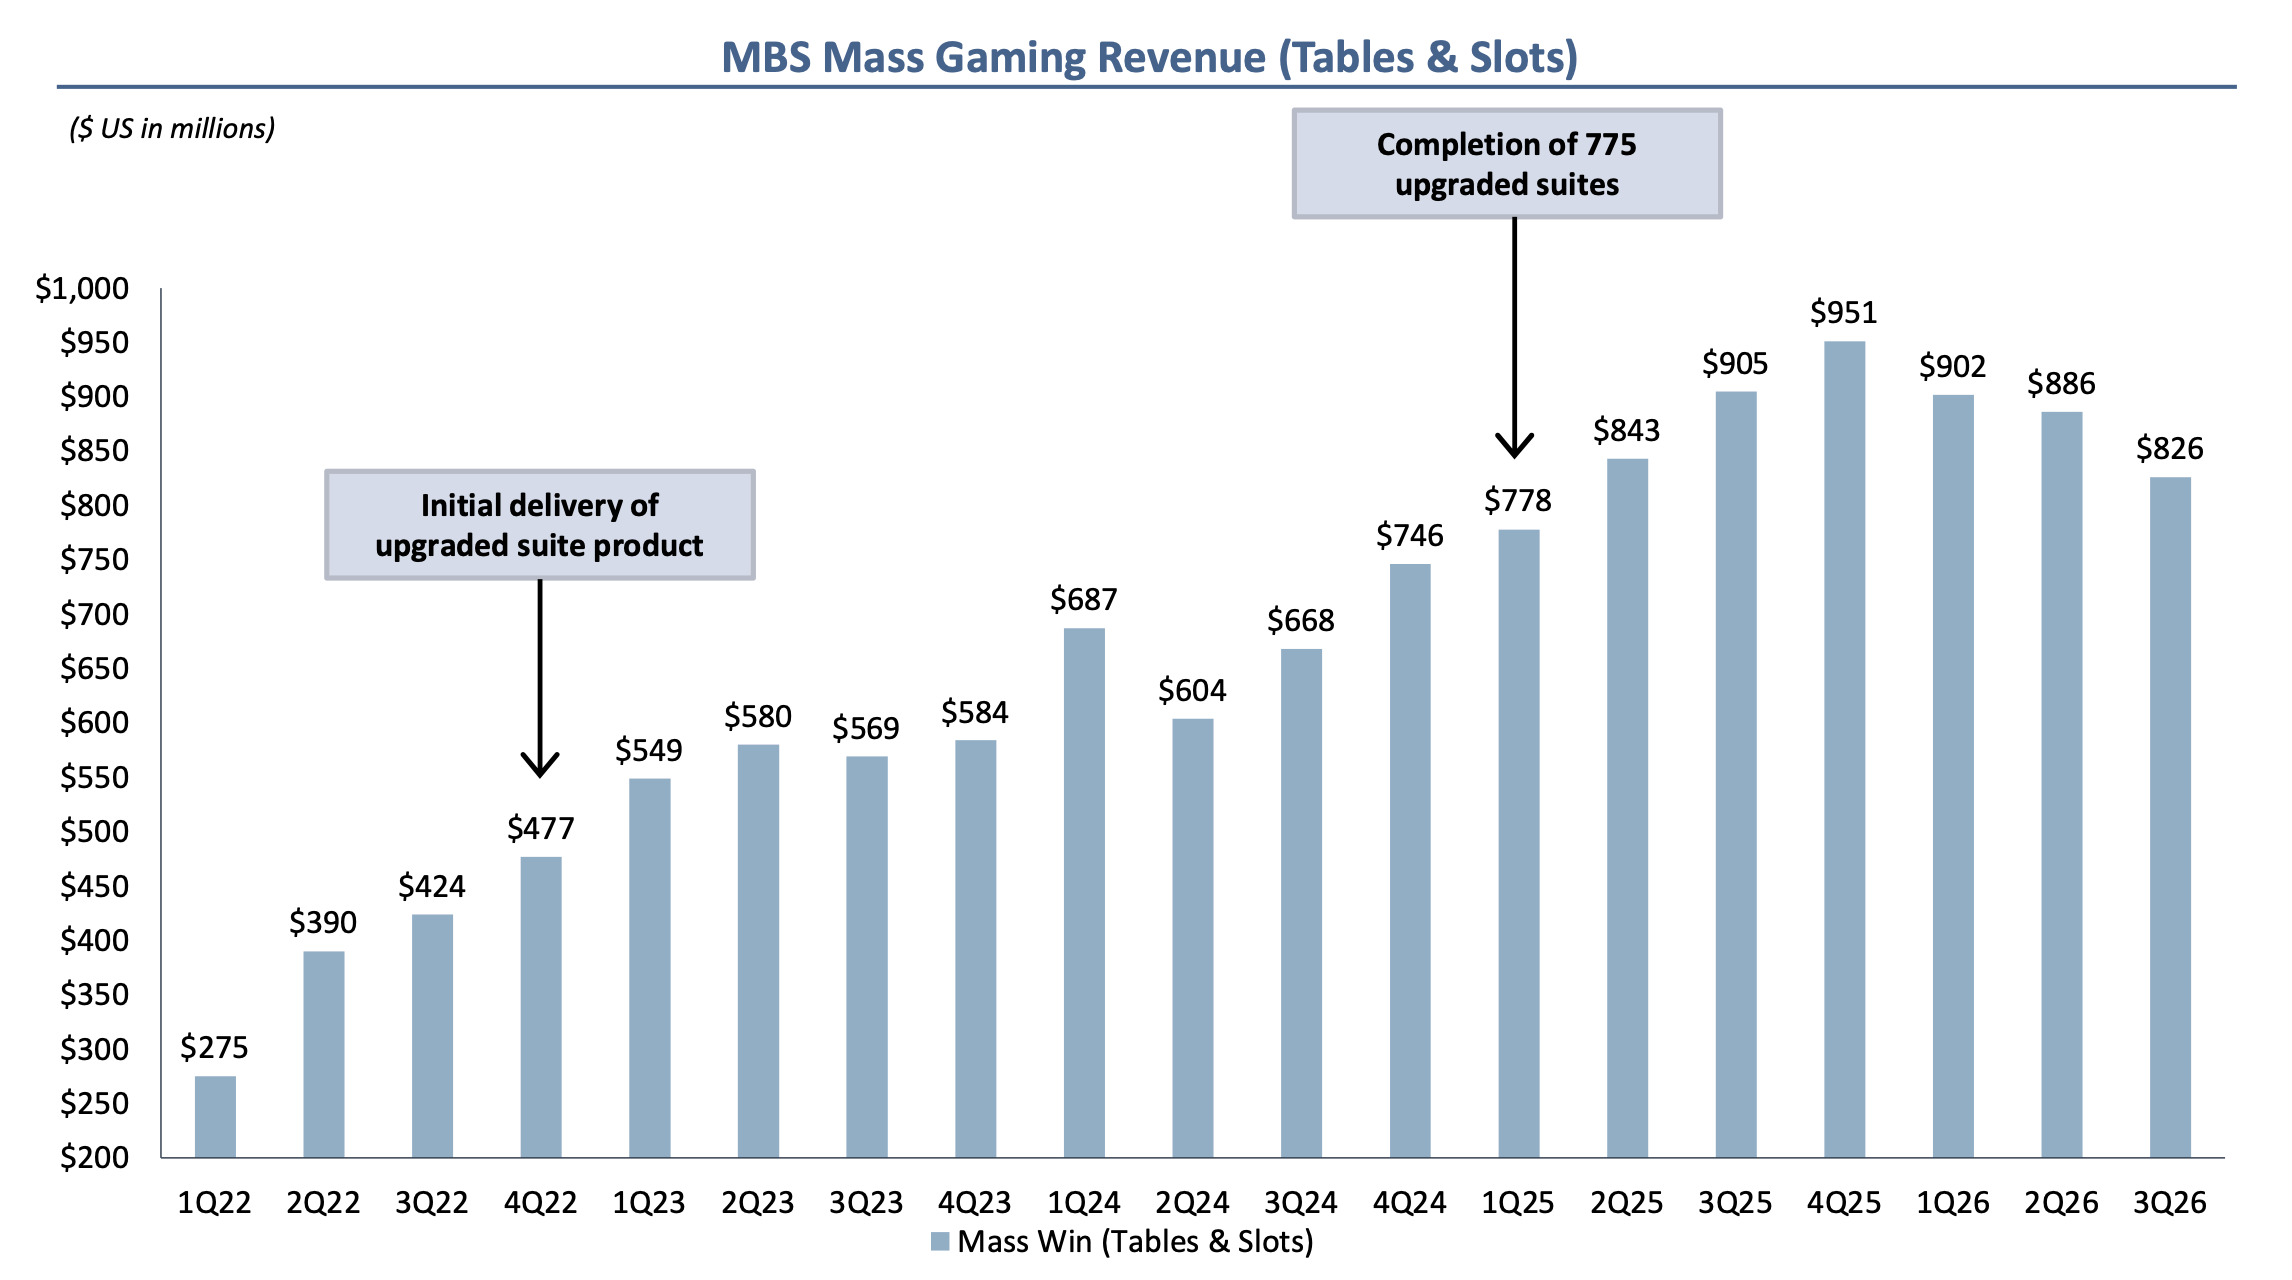
The positive surprise has been Singapore. Revenues for Singapore in 2025 were $5.6bn versus the $4.5bn we expected. That extra $1.1bn in Singapore made up for the shortfall in Macau.
But here you see the problem and why LVS shares are $36.
Q2 revenues in Singapore were flat. Then in Q3 growth went negative.
We already had problems with Macau.
Now the Golden Goose is struggling too.
So what’s going on?
What do we do?
