

It’s time. Time for the rubber to meet the road.
Time to assess the quarterly performance of our strategies.
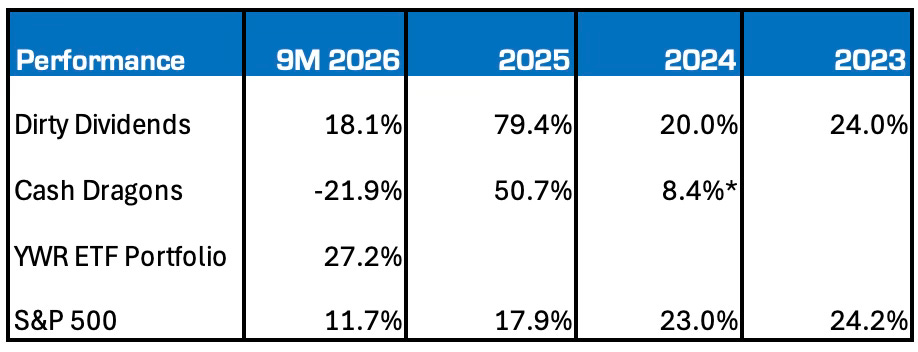
As a reminder Dirty Dividends, our longest running strategy, was born at the height of the European ESG madness in 2023. This was when funds didn’t want to invest in anything to do with mining, energy, autos, banks and tobacco. It has evolved over time, but still remains biased towards value, and dividends.
Cash Dragons was born in late 2024 at the height of China’s uninvestableness.
The YWR ETF portfolio is a new creation where we work together to create a simple, low-cost global allocation portfolio using ETF’s.
Aside from Cash Dragons, we are having a good year.
YWR ETF Portfolio
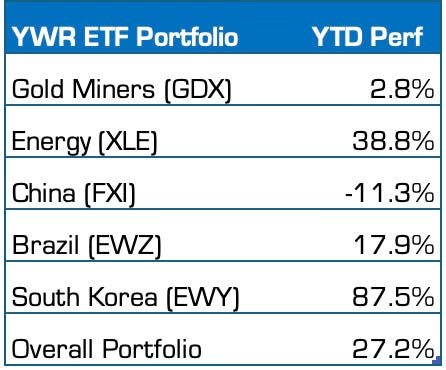
I like this portfolio.
If you remember back in December 2025 we surveyed the YWR community on their top ETF picks for 2026 (YWR 2026 Asset Allocation).

Usually, I fade investor surveys and do the opposite, but since this was YWR readers, the elites of the financial community, we took the picks at face value and went with what everyone liked. I made one tactical overlay though, which was to add the Korea ETF (EWY). We started the year with five ETF’s all at a 20% weighting.
YTD the portfolio is +27%. It’s been really helpful that we were bullish energy when nobody else was. Brazil is also performing well. It was challenging to stick with Brazil during the depths of despair, but now it is working and if the election goes our way has more to go. Real interest rates in Brazil are at Africa levels. Surprisingly, gold miners, which everyone loved earlier in the year, have been a dud ytd. China, which I keep pushing, has been the worst performer :(
We haven’t traded the ETF portfolio all year, but there were two decision points where we considered shifting our positioning, yet didn’t.
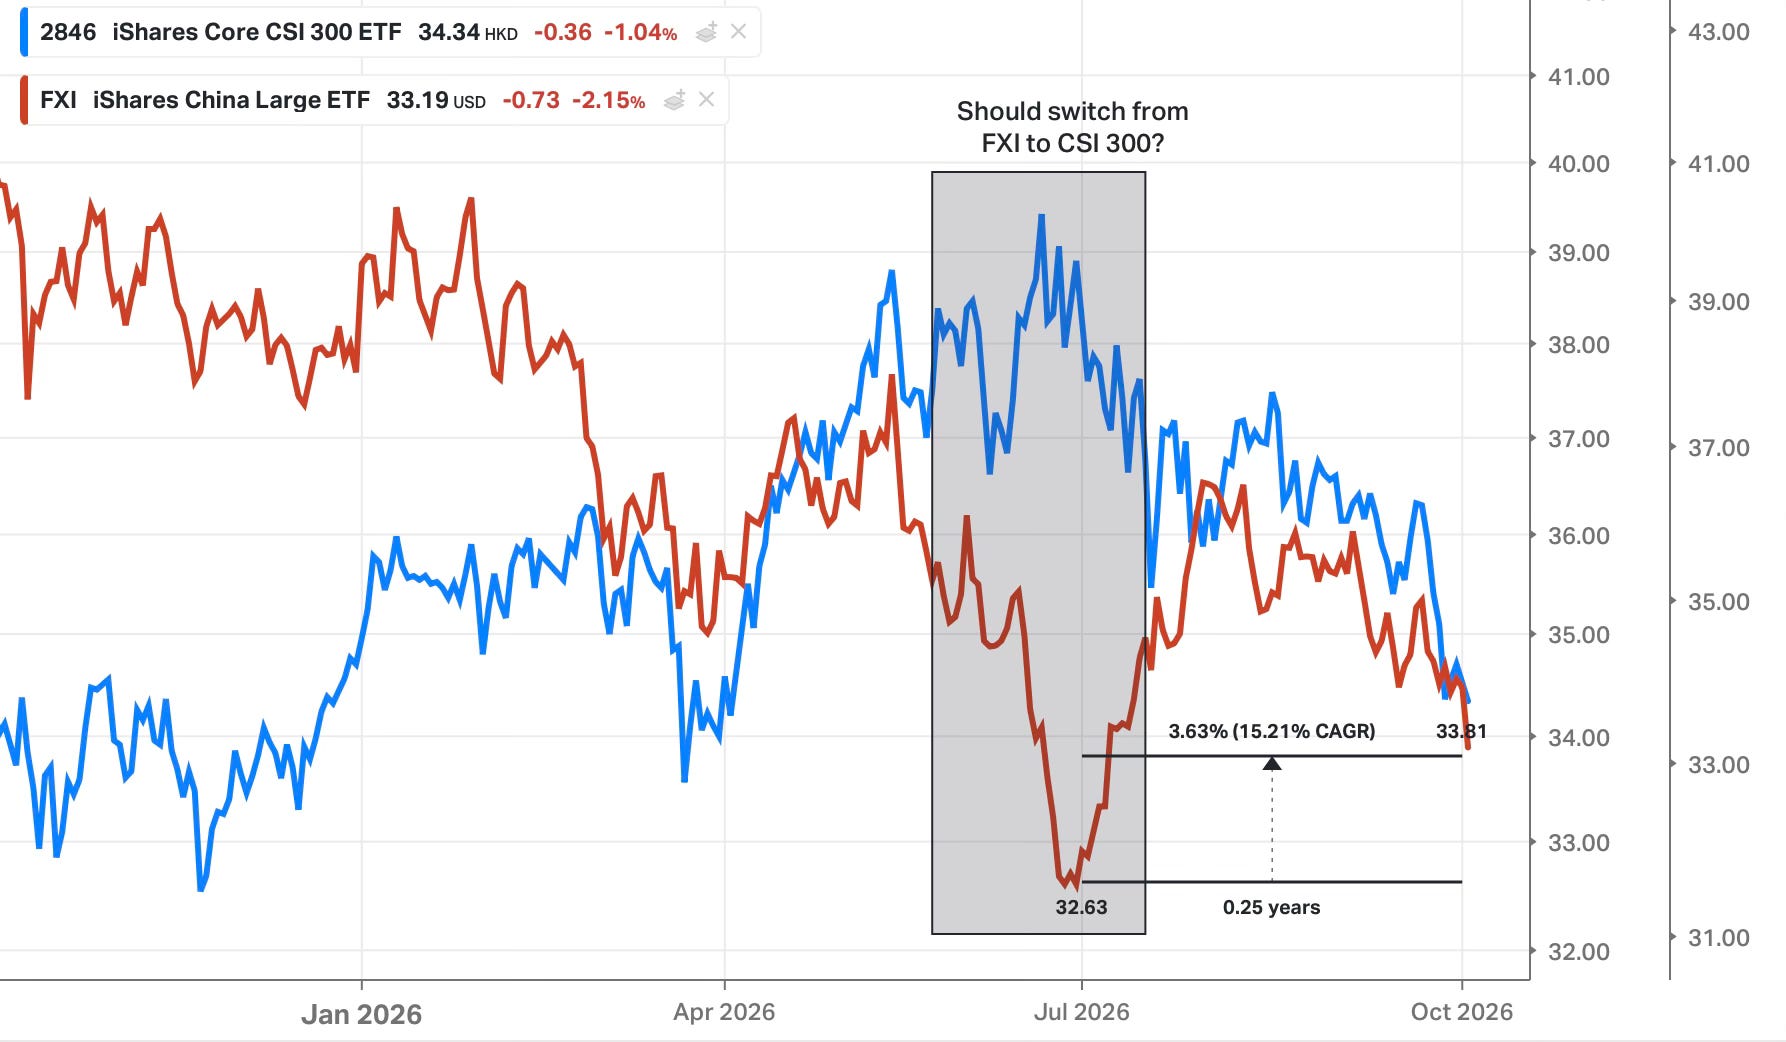
At the end of Q2 we were frustrated that China CSI 300 with all the cool AI optical companies like Zhongi Innolight and Eoptolink was outperforming our FXI portfolio of loser software companies and banks. We were considering switching to the CSI 300. Thankfully, we stuck with FXI and didn’t get whipsawed into buying CSI at the top.
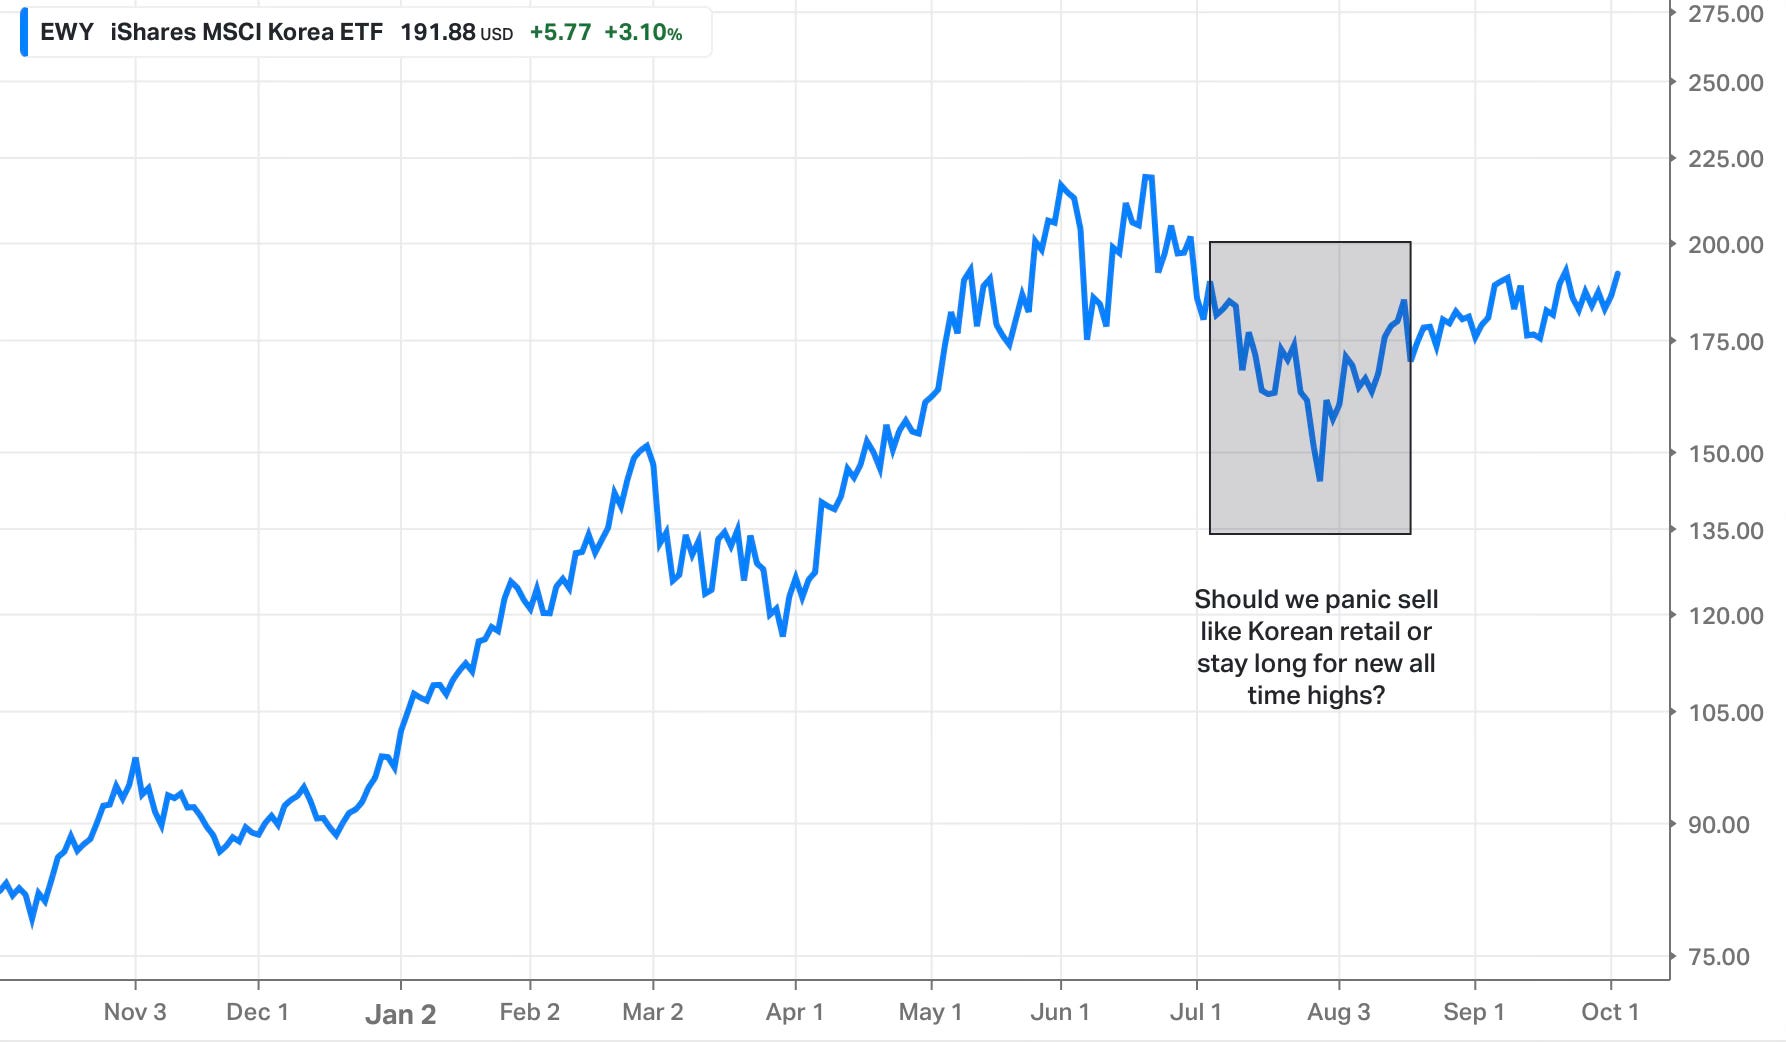
Our other decision point was whether to panic sell Korea on the lows when all the leveraged retail traders got margin called in July. We decided the July sell-off was most likely a buying opportunity, not a time to sell. Our oversized imagination could see Korea going on to confound the memory bears and make new all time highs and we wanted to be on board for that. So we did nothing.
Below is our current allocation after the YTD performance.
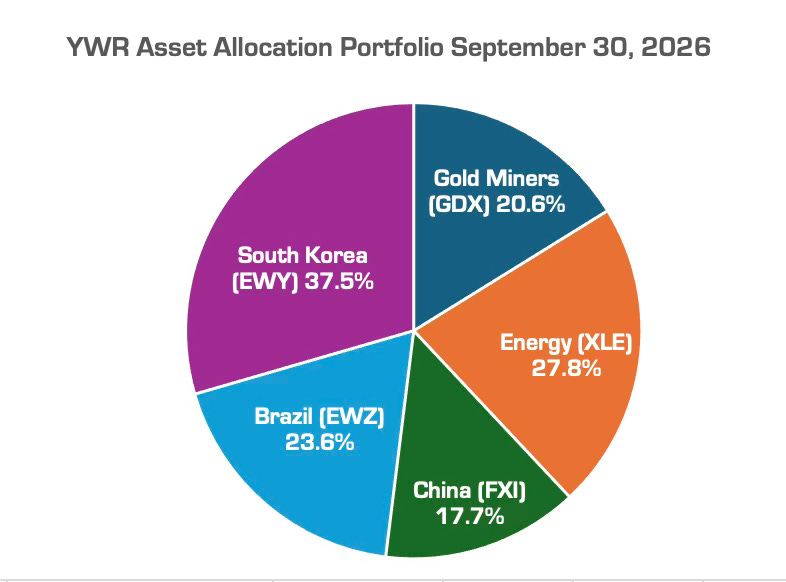
I like how the portfolio is performing and I like how diversified it is. Our five themes have low correlation with each other. We are +27% ytd and still have gold and China in our back pocket.
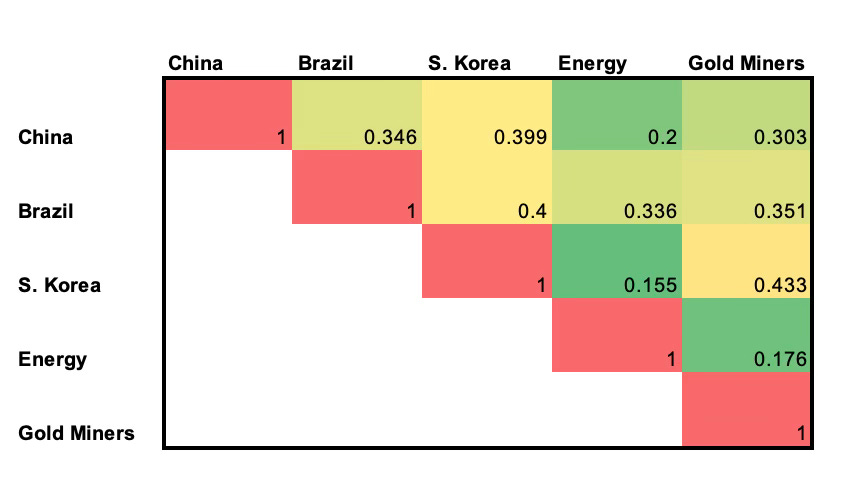
BTW: This risk analysis was created by Stevie. Just give Stevie the tickers you want and ask him to build you a 5 year correlation heat map in Google Sheets.
Dirty Dividends
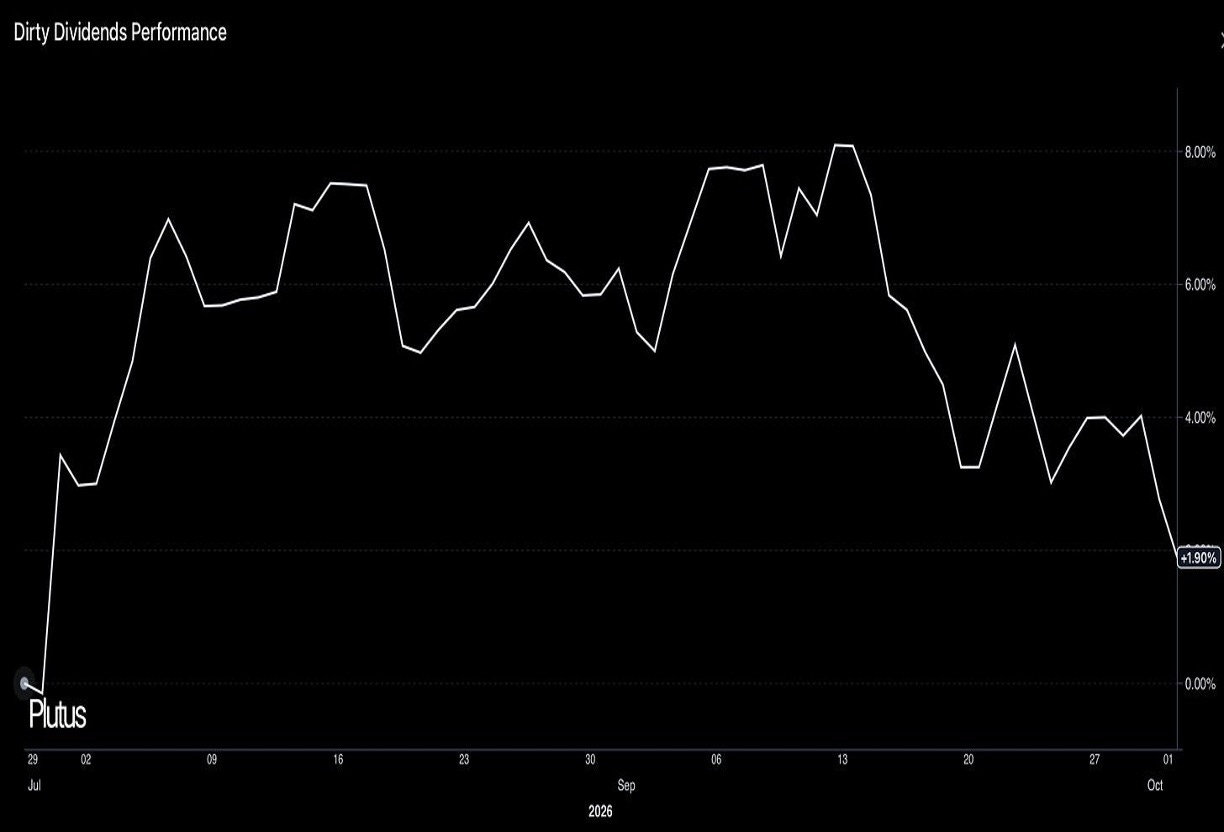
Dirty Dividends was +15% in 1H 2026 and added another 1.9% in Q3.
*A note on performance tracking. Starting in July I switched to using Portfolios on Run Plutus to track Dirty Dividends and the Cash Dragons.
The only trade during the quarter was to reduce Jackson Financial (JXN) from 7% to 5%. We bought it back in April 2023 (A Friday Money Maker) at $36 and it’s +260% (not including the dividends).
I don't want to be a chicken little, but I am wary of this increased use of reinsurance captives in the life insurance industry. I think I understand what Jackson is doing, why they set up BrookeRe and why the hedge accounting would look funny if the S&P went up unrelentingly (which it has), but I also appreciate what I don’t know. We always knew some a life insurance accounting bear case would raise its ugly head at some point, although it is also why Jackson trades on 5x earnings because nobody understands it. Let’s recognise that we’ve done well while there is now potentially something which we do not understand, and take some profits.
During the quarter we also reinvested some dividends into Frontline (a Tuesday Money Maker). In hindsight we should have made Frontline bigger.
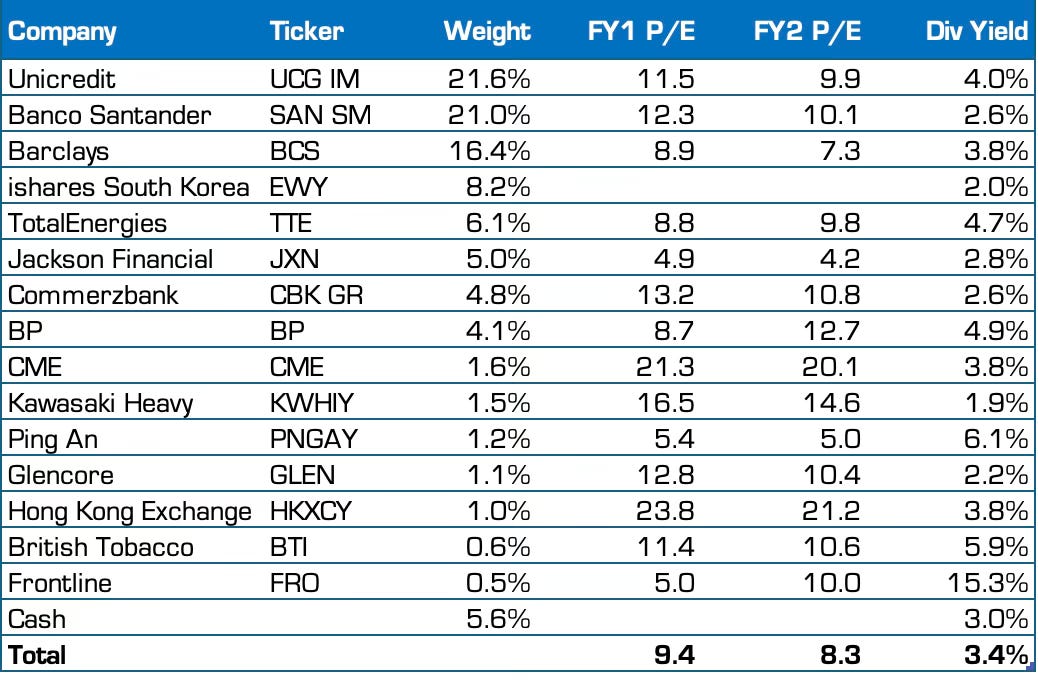
Dirty Dividends is massively exposed to European banks and the fear this week is that the rise in long-term yields in Europe will be negative for the banks. I understand the concern, it makes sense, but I’m not selling. To me this is stage 2 of the trend towards higher interest rates in Europe. Eventually, the banks will benefit. The ECB will gradually, or not so gradually, raise their policy rates to new highs, and with a lag bank interest margins will widen further, kicking off higher earnings and higher share prices. 2022 all over again. In the meantime we have to sit through the volatility.
Cash Dragons
Sheesh. It’s been a tough year for the Cash Dragons.
The strategy is -20% ytd and underperforming FXI. The big difference is we haven’t owned Chinese banks, which have been the star performers. Ping An, our main financial holding, which had good results, is down 22% YTD.
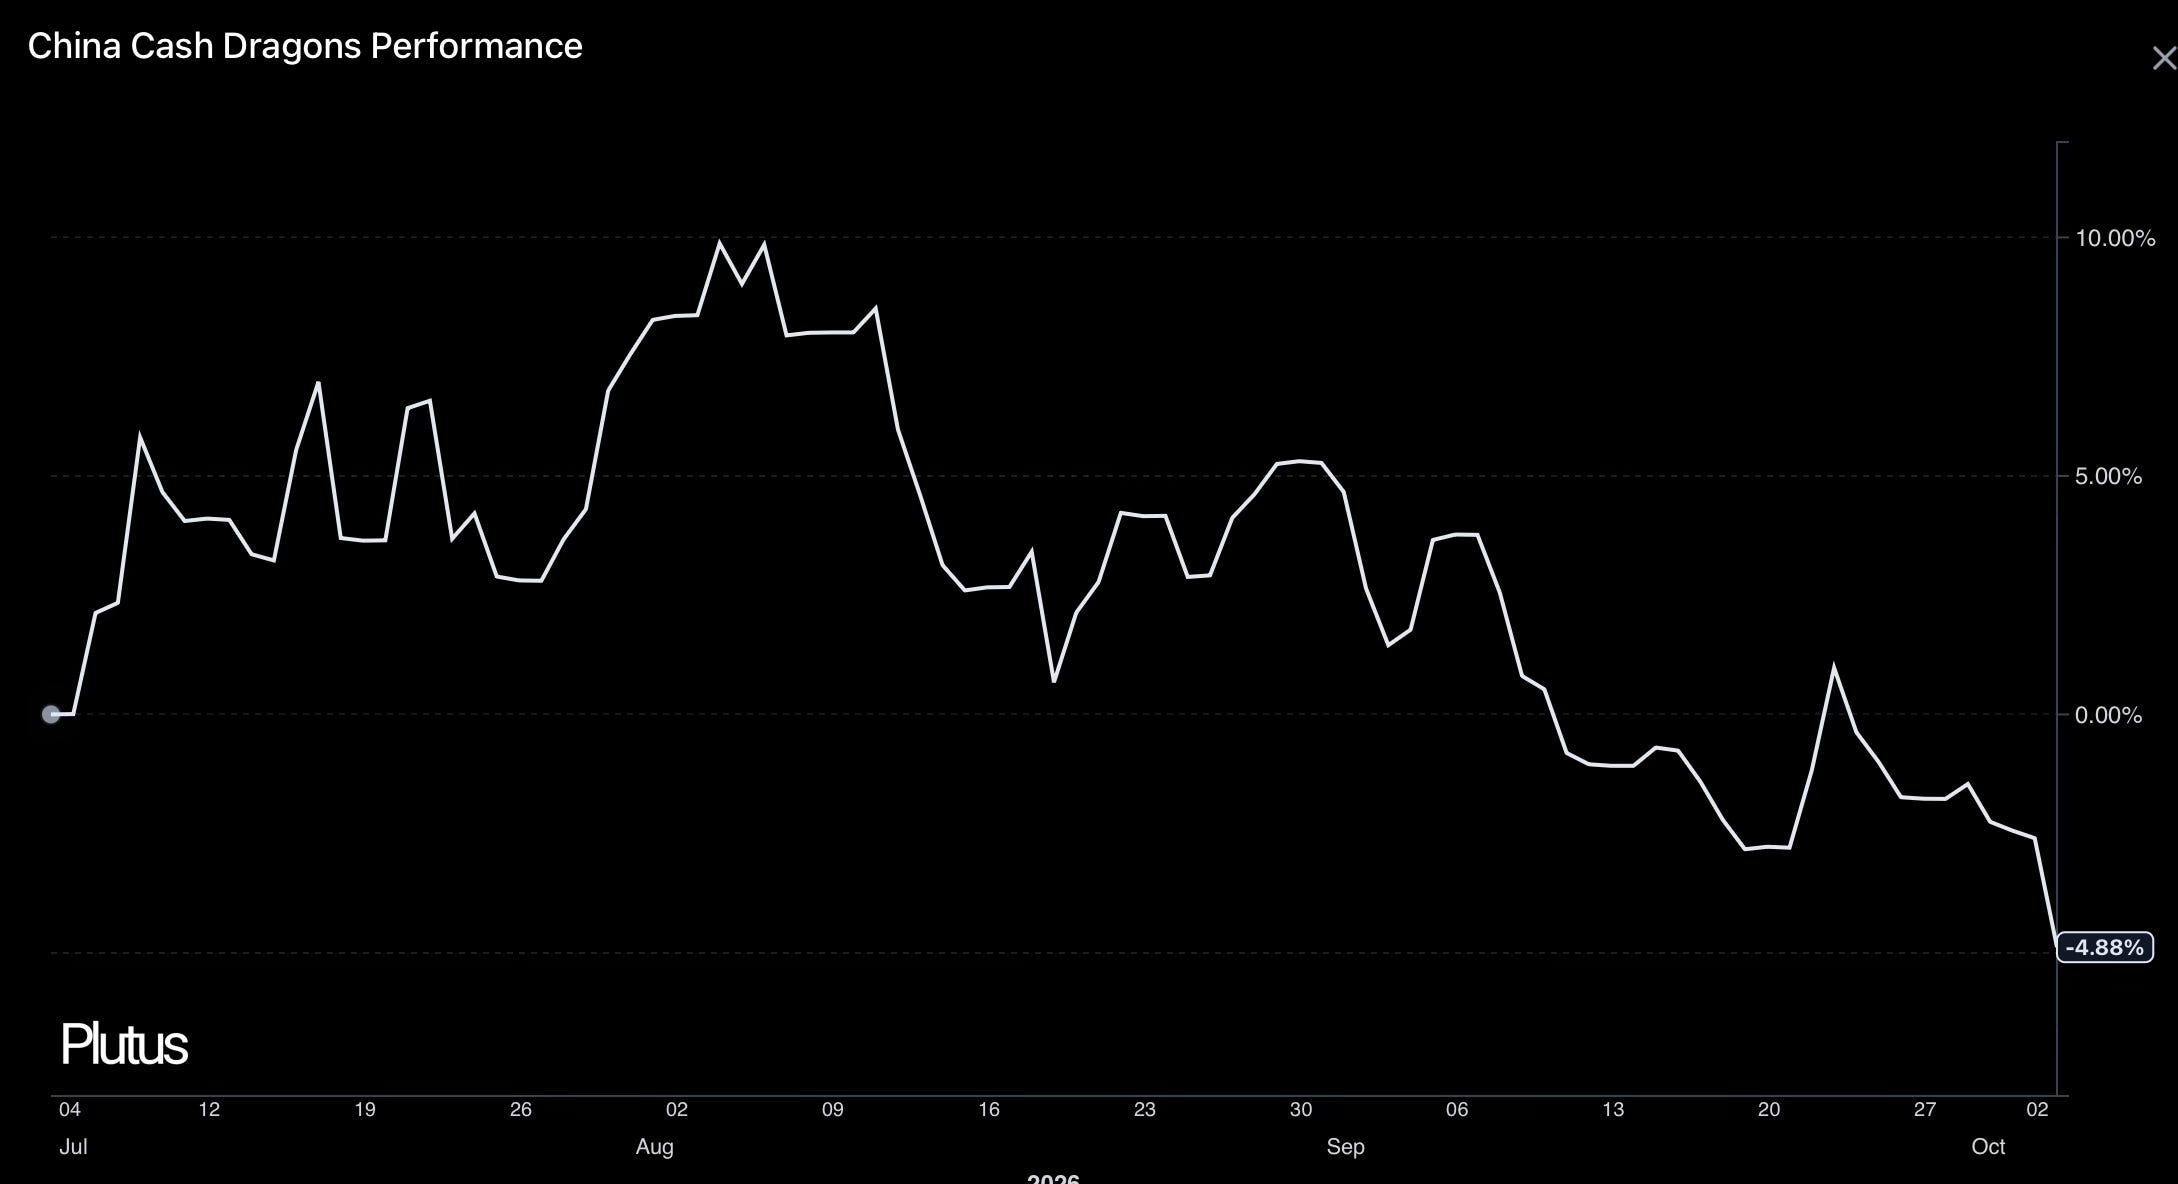
I have to say I did not predict the implosion of China’s leading tech companies. I should clarify. Alibaba and Baidu imploded, while Tencent has been more of a derating. TenCent’s core business is holding up well. The market is just not thrilled about the growth in AI related costs.
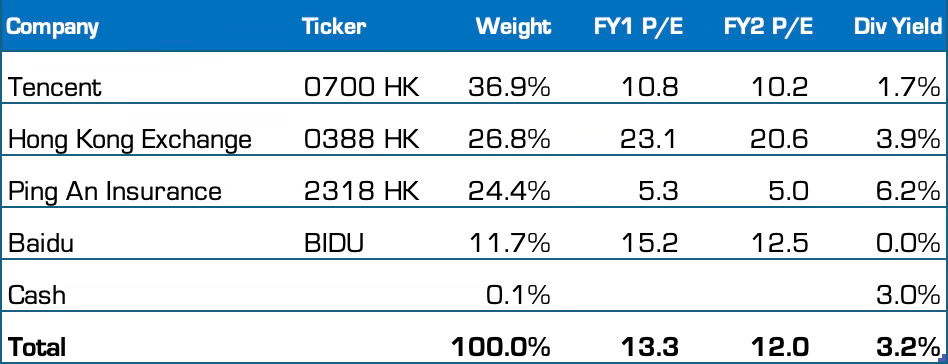
As I said earlier Ping A results were solid and estimate revisions are positive. Hong Kong Exchange results have also been good. The exchange is benefitting from higher trading volumes and record IPO issuance.


I’m sticking with our China stocks and still think this is going to work astoundingly well, but as noted in the Q2 2026 Performance Review I did reduce my personal exposure to the Cash Dragon theme. Partly because my conviction around the tech company results was slipping, but also because it was the most tax efficient way to raise money to buy some real estate.
Summary
We thank the market gods for a good year so far, and if it is not too much to ask, would love to see China, Brazil and Gold have a stonking Q4.
Note: All the YWR Portfolios, both current and past are available at YWR Portfolios.
Have a good fall weekend.
Erik